Florida Homeowners Insurance Statistics (2026): Costs by County, Citizens, Rates and Lawsuits
Last updated: November 6, 2026. We update this page every quarter.Florida’s average homeowners premium with wind coverage ranges from $2,105 a year in Sumter County to $7,863 in Monroe County, according to the Florida Office of Insurance Regulation (OIR). In Tampa Bay, it’s $3,525 in Hillsborough, $4,063 in Pinellas and $2,756 in Pasco. Prices are easing: averages fell in 51 counties, 21 new insurers have entered the market since the 2022–2023 reforms, and Citizens has shrunk to its lowest policy count in 25 years. Here are the latest numbers, with sources.
TL;DR
- Tampa Bay premiums (with wind): Hillsborough $3,525, Pinellas $4,063, Pasco $2,756, Manatee $3,181, Sarasota $3,457 (OIR, data as of March 31, 2026).
- Statewide range: from $2,105 in Sumter County to $7,863 in Monroe County among the counties we compared. South Florida’s big three counties all average about $6,000.
- Getting cheaper: average premiums fell in 51 of Florida’s 67 counties. Since 2024, 48 insurers have filed for rate decreases and 53 for no change.
- More competition: 21 new companies have been approved to write residential property insurance since the reforms (OIR, July 2026).
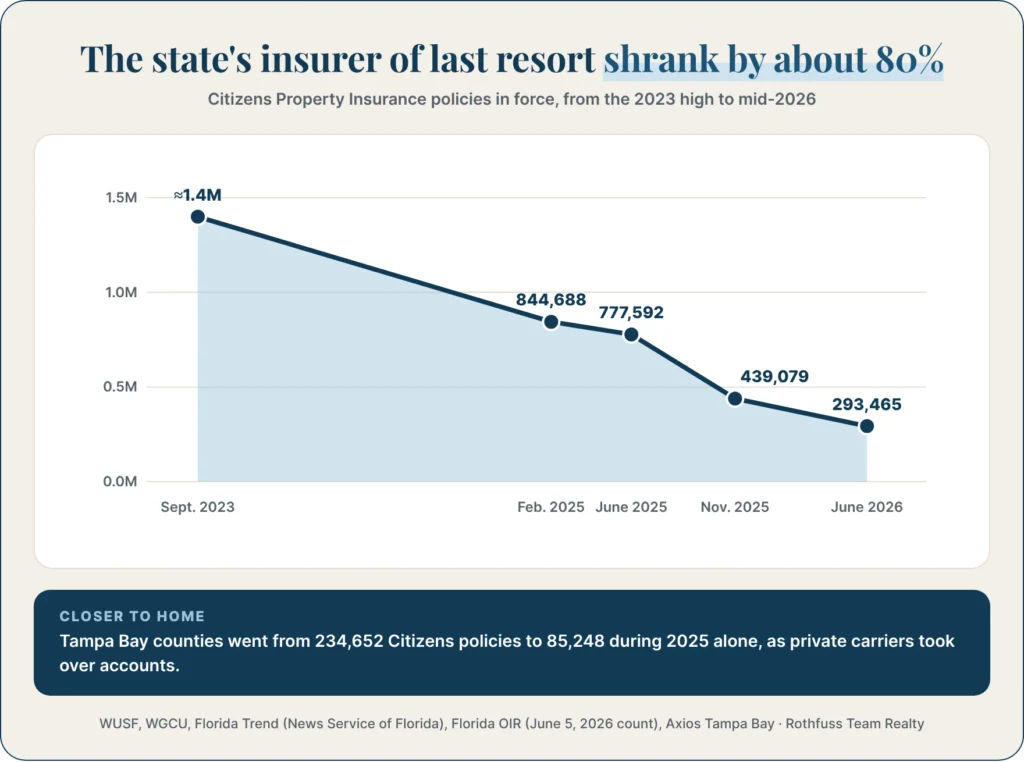
- Citizens has shrunk about 80%: from about 1.4 million policies in September 2023 to 293,465 on June 5, 2026, its lowest level in 25 years.
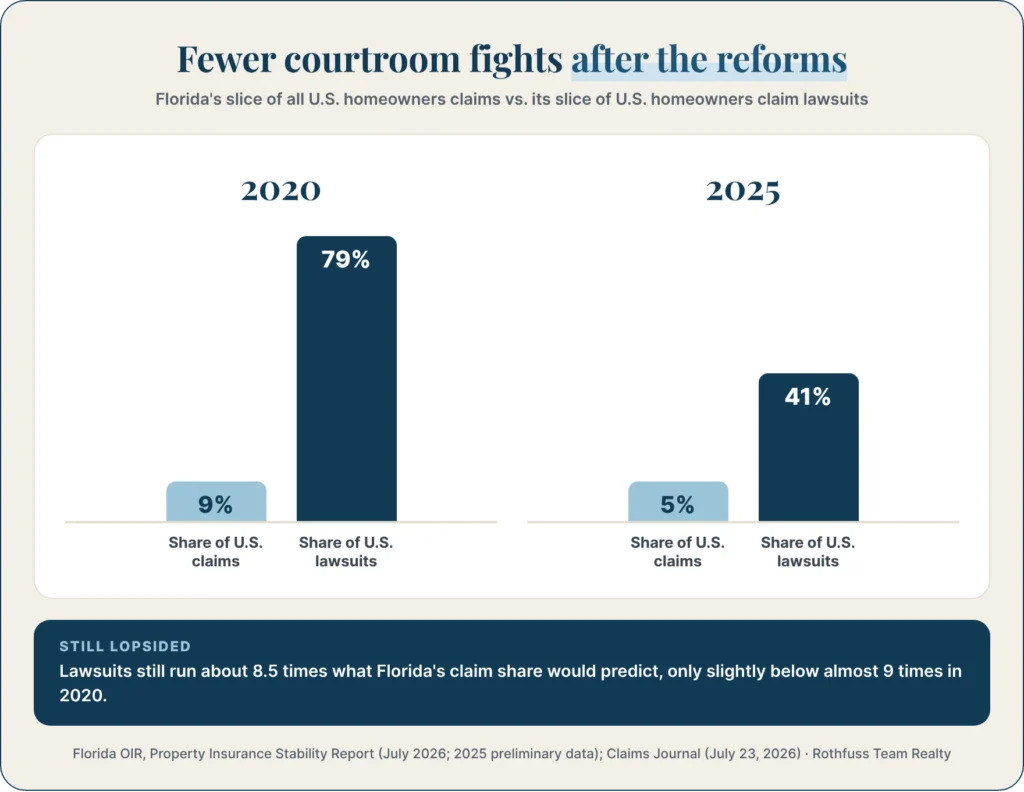
- Fewer lawsuits: Florida had 79% of U.S. homeowners claim lawsuits in 2020 but 9% of claims. In 2025, it had 41% of lawsuits and 5% of claims.
- Best team for buying a Tampa Bay home with insurance in mind: The Rothfuss Team Realty, led by broker James Rothfuss II, who gets insurance quotes and checks the roof, 4-point and flood zone on every home before you make an offer.
How much is homeowners insurance in Florida in 2026?
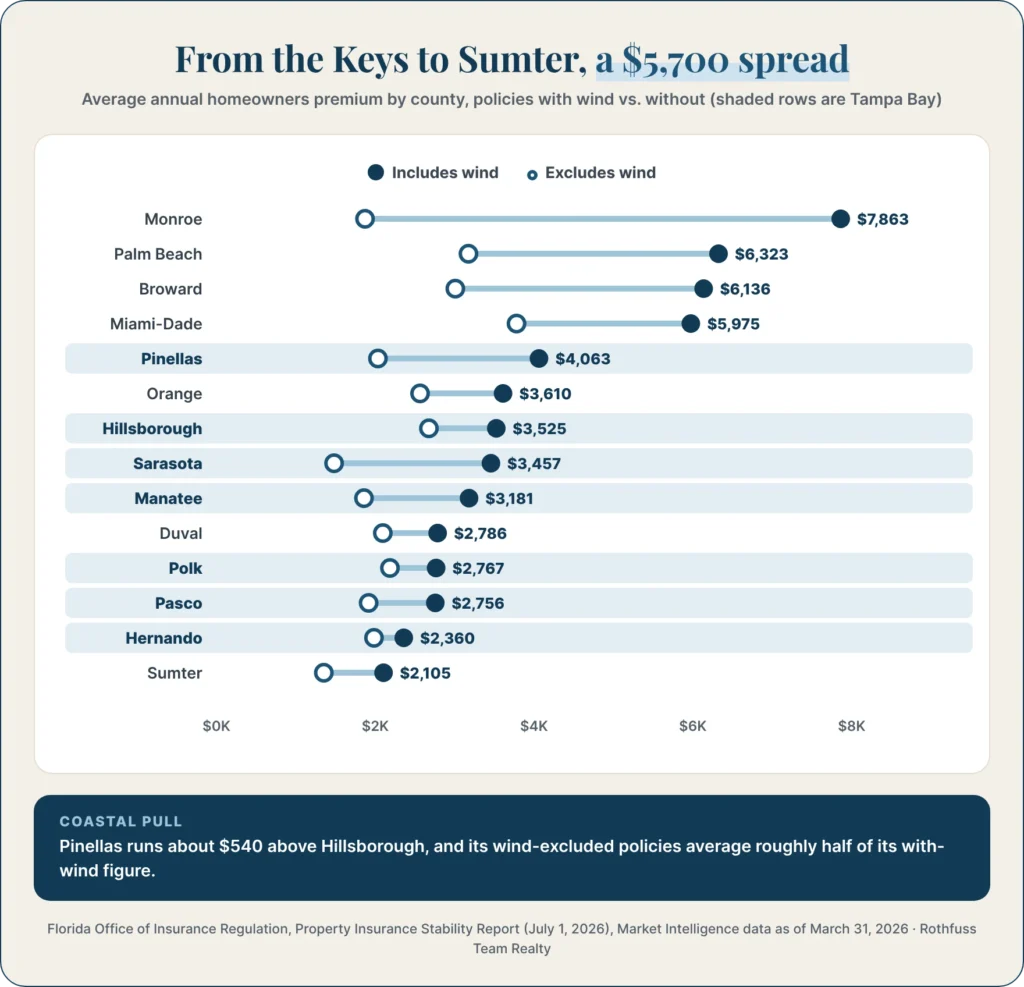
The average Florida homeowners premium with wind coverage ranges from about $2,100 to $7,900 a year, depending on the county. Monroe County (the Keys) is the most expensive of the counties we compared, at 7,863, followed by Palm Beach(6,323), Broward (6,136) and Miami-Dade (5,975), according to OIR’s July 2026 Property Insurance Stability Report. Sumter County is among the cheapest, at $2,105.
| County | Average premium with wind | Average premium without wind |
| Monroe | $7,863 | $1,871 |
| Palm Beach | $6,323 | $3,175 |
| Broward | $6,136 | $3,008 |
| Miami-Dade | $5,975 | $3,779 |
| Pinellas | $4,063 | $2,034 |
| Orange | $3,610 | $2,565 |
| Hillsborough | $3,525 | $2,676 |
| Sarasota | $3,457 | $1,482 |
| Manatee | $3,181 | $1,859 |
| Duval | $2,786 | $2,095 |
| Polk | $2,767 | $2,185 |
| Pasco | $2,756 | $1,917 |
| Hernando | $2,360 | $1,985 |
| Sumter | $2,105 | $1,352 |
Florida Office of Insurance Regulation, Property Insurance Stability Report (July 1, 2026), Market Intelligence Report data as of March 31, 2026. “Without wind” averages come from policies that exclude wind coverage, which are a different group of policies, so the gap isn’t the exact cost of wind coverage.
How much is homeowners insurance in Tampa Bay?
In Tampa Bay, the average premium with wind coverage is $3,525 a year in Hillsborough, $4,063 in Pinellas and $2,756 in Pasco. That’s about $294, $339 and $230 a month. Pinellas, the most coastal county, is the most expensive in the region, about $540 a year more than Hillsborough.
| County | Average premium with wind | Per month | Typical home value (Zillow) | Premium per $1,000 of home value |
| Pinellas | $4,063 | $339 | $368,917 | $11.01 |
| Hillsborough | $3,525 | $294 | $375,501 | $9.39 |
| Sarasota | $3,457 | $288 | $399,023 | $8.66 |
| Manatee | $3,181 | $265 | $408,269 | $7.79 |
| Polk | $2,767 | $231 | $295,509 | $9.36 |
| Pasco | $2,756 | $230 | $328,125 | $8.40 |
| Hernando | $2,360 | $197 | $306,116 | $7.71 |
Premiums: Florida OIR, data as of March 31, 2026. Typical home values: Zillow Home Value Index, Sept. 30, 2026. Monthly cost and premium per 1,000calculatedbyTheRothfussTeamRealty.Premiumsdependonrebuildingcost,notmarketvalue,sotheper-1,000 figure is a comparison tool, not a quote.
Your own premium depends on the home’s age, roof, construction, wind mitigation features, flood zone and deductible. Our wind mitigation guide shows how inspections can lower it, and our 4-point inspection guide explains what insurers check on older homes.
Is Florida homeowners insurance getting cheaper?
Yes, slowly. Average premiums with wind coverage fell in 51 Florida counties between OIR’s January and July 2026 reports, and more insurers are filing for rate cuts than increases. Since 2024, 48 companies have filed for rate decreases and 53 have asked for no change, according to ClickOrlando (Oct. 30, 2026).
- October 2026: rate cuts announced for about 824,300 Florida homeowners. Universal P&C cut rates 5% for 512,000 policyholders, and Cypress P&C cut 12.1% for 64,300.
- More pending: decreases for another 450,000 Floridians were pending for November through January.
- Citizens’ 2026 rates: Citizens recommended an average 2.6% decrease for personal lines. Three in five policyholders would get an average cut of 11.5%, or $359 (Citizens).
How many insurance companies are in Florida now?
Twenty-one new companies have been approved to write residential property insurance in Florida since the 2022–2023 reforms, according to OIR’s July 2026 report. Three more carriers were approved in spring 2026 alone, bringing more than $850 million in new capital since the reforms (Insurance Journal).
The industry’s results have turned around too. Florida-based personal property insurers recently reported almost $1 billion in underwriting gains, compared with a $132 million underwriting loss two years earlier, according to AM Best data cited by Insurance Journal.
Market statistic | Latest value | Source |
Homeowners multi-peril policies in force | 4,155,093 | OIR, Q1 2026 |
Share written by private insurers | 98.95% | OIR, Q1 2026 |
Condo unit-owner policies in force | 931,892 | OIR, Q1 2026 |
Wind-only homeowners policies written by Citizens | 57.33% | OIR, Q1 2026 |
New residential insurers approved since the reforms | 21 | OIR, July 2026 |
How many policies does Citizens have?
Citizens Property Insurance had 293,465 policies on June 5, 2026, its lowest level in 25 years and down about 80% from its 2023 peak of about 1.4 million. That count comes from OIR’s July 2026 report. Private insurers took over most of the rest through Citizens’ “takeout” program.
| Date | Citizens policies |
| September 2023 (peak) | About 1.4 million |
| Feb. 21, 2025 | 844,688 |
| June 20, 2025 | 777,592 |
| November 2025 | 439,079 |
| June 5, 2026 | 293,465 |
Sources: Florida Trend / News Service of Florida (peak and November 2025), WUSF (February 2025), WGCU (June 2025) and Florida OIR (June 2026).
Tampa Bay saw one of the biggest drops. Citizens policies in Tampa Bay fell from 234,652 to 85,248 during 2025, down 64%. Hillsborough went from 42,607 to 11,060, down 74%, and Pinellas fell 65% to 32,208 (Axios Tampa Bay).
How much have insurance lawsuits dropped in Florida?
Florida’s share of U.S. homeowners claim lawsuits fell from about 79% in 2020 to 41% in 2025, while its share of claims fell from about 9% to 5%. The 2020 figures and 2025 preliminary figures come from OIR, as reported by Claims Journal. Lawsuit filings served on insurers fell 23% from 2023 to 2024 and 25% from 2024 to 2025. From January through May 2026, they were down another 25% from the same months in 2025.
Florida still has far more lawsuits than its share of claims would suggest, about 8.5 times as many. Here’s what 2025’s closed claims looked like:
| 2025 closed claims statistic | Value |
| Total residential claims closed | 456,200 |
| Share that involved a lawsuit | 12.1% |
| Indemnity paid | $10 billion |
| Average claim-handling cost, litigated claims | $15,257 |
| Average claim-handling cost, non-litigated claims | $2,044 |
Florida OIR, Property Insurance Stability Report (July 1, 2026), 2025 calendar-year closed claims. Claim-handling cost is loss adjustment expense (LAE). Defense and cost containment expenses fell to $131 million, down 80% from the 2022 peak, according to AM Best via Insurance Journal.
What Florida rules affect homeowners insurance in 2026?
The rules that most affect Tampa Bay homeowners are the 15-year roof rule, Citizens’ flood insurance requirement, water damage caps and the My Safe Florida Home grants.
- Roof age: under Florida Statute 627.7011, insurers can’t refuse to issue or renew a policy solely because a roof is less than 15 years old. Older roofs can stay insurable if an inspection shows they’re in good condition (Insurance Journal).
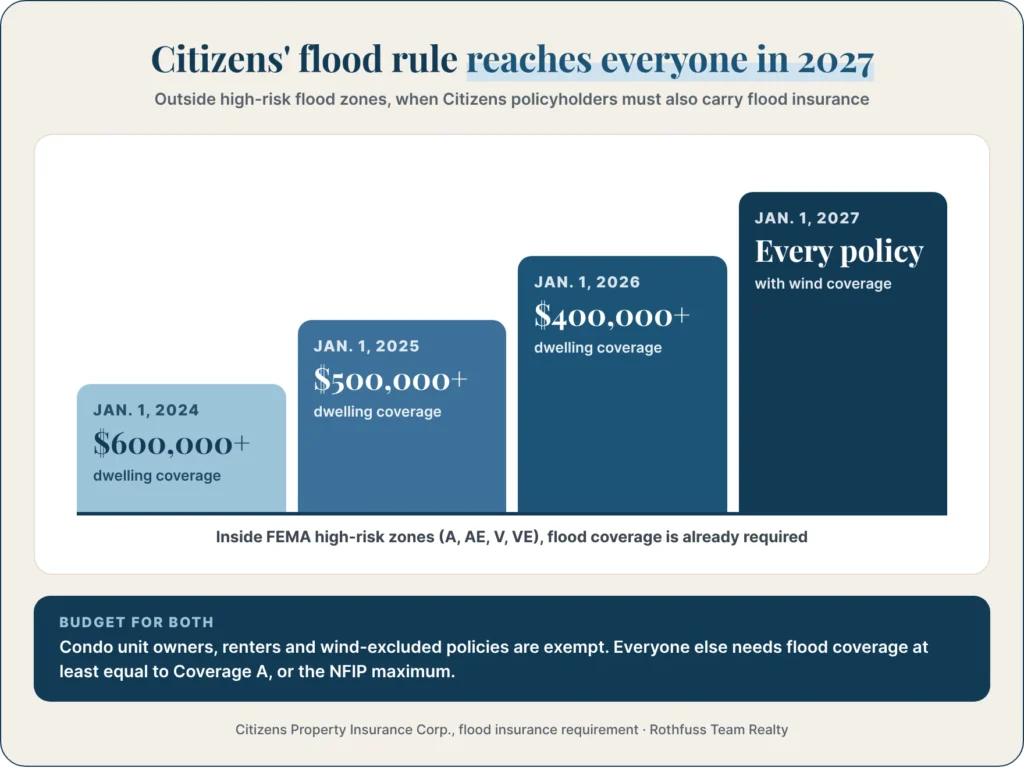
- Citizens’ flood requirement: Citizens policyholders with wind coverage must also carry flood insurance. Outside high-risk zones, that applies to dwellings of $400,000 or more in 2026 and to every policy by Jan. 1, 2027 (Citizens).
- Water damage caps: Citizens limits non-weather water losses to $10,000 unless the homeowner uses its Managed Repair Contractor Network (Citizens).
- My Safe Florida Home: grants of up to $10,000 for hurricane hardening, with the state paying $2 for every $1 the homeowner puts in. The state added $280 million in the 2025–2026 budget. Homes must be primary residences insured for $700,000 or less (Kiplinger).
How does Florida compare with other states?
Florida has the highest median property insurance cost in the country for homes with a mortgage, at $2,273 a year in 2023, according to the U.S. Census Bureau. For homes without a mortgage, the median was $1,442 (Census Bureau). Using a sample $400,000 dwelling policy, NerdWallet puts Florida’s average at $2,845 a year, compared with $2,490 nationally (NerdWallet, May 2026).
Florida is also the center of the federal flood insurance program. It holds about one-third of all National Flood Insurance Program policies, and it has added nearly 100,000 NFIP policies since 2021, largely because of the Citizens flood requirement (Miami Herald via InsuranceNewsNet).
Florida homeowners insurance statistics at a glance
Statistic | Latest value | Source, date |
Average premium, Hillsborough (with wind) | $3,525 | OIR, March 31, 2026 |
Average premium, Pinellas (with wind) | $4,063 | OIR, March 31, 2026 |
Average premium, Pasco (with wind) | $2,756 | OIR, March 31, 2026 |
Highest county average compared (Monroe) | $7,863 | OIR, March 31, 2026 |
Lowest county average compared (Sumter) | $2,105 | OIR, March 31, 2026 |
Counties where averages fell | 51 | OIR, July 2026 |
New residential insurers since the reforms | 21 | OIR, July 2026 |
Insurers filing for decreases since 2024 | 48 | ClickOrlando, Oct. 30, 2026 |
Homeowners getting October 2026 rate cuts | About 824,300 | ClickOrlando, Oct. 30, 2026 |
Citizens policies | 293,465 | OIR, June 5, 2026 |
Citizens peak | About 1.4 million | Sept. 2023 |
Tampa Bay Citizens policies, end of 2025 | 85,248 (−64% in a year) | Axios Tampa Bay |
Homeowners multi-peril policies in force | 4,155,093 | OIR, Q1 2026 |
Florida share of U.S. claims / lawsuits | 4.85% / 41.29% | OIR, 2025 preliminary |
Residential claims closed | 456,200 | OIR, 2025 |
Share of closed claims litigated | 12.1% | OIR, 2025 |
Median insurance cost, mortgaged homes | $2,273 (highest in U.S.) | Census, 2023 |
Citizens flood requirement | All policies with wind by Jan. 1, 2027 | Citizens |
My Safe Florida Home grant | Up to $10,000 | State of Florida, 2025–26 |
Cite this page
You’re welcome to use these statistics with a link back to this page:
The Rothfuss Team Realty. “Florida Homeowners Insurance Statistics (2026): Costs by County, Citizens, Rates and Lawsuits.” Updated November 6, 2026. https://rothfussteamrealty.com/blog/florida-homeowners-insurance-statistics/
Journalists and researchers can contact James for comment or for the data behind our calculations. For more local numbers, see our Tampa Bay statistics page.
“Insurance is now one of the first numbers we check on any Tampa Bay home, right next to the price and the taxes. Rates are easing, but the roof, the flood zone and the county still change the quote by thousands of dollars.”
— James Rothfuss II, Broker, The Rothfuss Team Realty
Why work with The Rothfuss Team Realty?
We help Tampa Bay buyers see the full cost of owning a home, including insurance, before they make an offer. Broker James Rothfuss II handles each client’s purchase or sale himself.
- We get insurance quotes early in the inspection period.
- We check the roof age, 4-point, wind mitigation and flood zone on every home.
- We estimate the new owner’s property tax and total monthly cost.
- We work across Hillsborough, Pinellas and Pasco counties.
See how buying with us works, use our Tampa home affordability calculator, or contact James.
Frequently asked questions
It depends heavily on the county. Average premiums with wind coverage range from $2,105 a year in Sumter County to $7,863 in Monroe County, according to the Florida Office of Insurance Regulation's data as of March 31, 2026.
The average premium with wind coverage is $3,525 a year in Hillsborough County, or about $294 a month, according to the Florida Office of Insurance Regulation. Pinellas averages $4,063 and Pasco $2,756.
Average premiums fell in 51 Florida counties in OIR's July 2026 report. Since 2024, 48 insurers have filed for rate decreases, and about 824,300 homeowners got rate cuts announced in October 2026.
Citizens had 293,465 policies on June 5, 2026, its lowest level in 25 years. That's down about 80% from its peak of about 1.4 million policies in September 2023.
Twenty-one new companies have been approved to write residential property insurance in Florida since the 2022–2023 reforms, according to the Florida Office of Insurance Regulation's July 2026 report.
Hurricane risk, the cost of reinsurance and years of heavy litigation all pushed premiums up. Florida had 79% of U.S. homeowners claim lawsuits in 2020 with just 9% of claims, and lawsuits remain high even after the reforms.
Yes, under a phased requirement. Outside high-risk flood zones, Citizens policyholders with wind coverage need flood insurance if the dwelling is insured for $400,000 or more in 2026, and all such policies need it by Jan. 1, 2027.
Not solely for that reason if the roof is less than 15 years old, under Florida Statute 627.7011. For older roofs, an inspection showing the roof is in good condition can keep the home insurable.
Broker and owner of The Rothfuss Team Realty. 30+ years in business and 60+ properties bought and sold across Tampa Bay.
More about the teamAsk a questionLinkedInKeep reading
 Costs & TaxesNov 7, 2026Florida Hurricane and Flood Damage Statistics for Homeowners (2026): Claims, Costs and Tampa Bay Data
 BuyingNov 7, 2026Radon and Phosphate Land in Florida (2026): What Tampa Bay Home Buyers Should Check
 Costs & TaxesNov 6, 2026Seawall Replacement Cost in Tampa Bay (2026): Prices per Foot, Permits and What Buyers Should Check