Should You Buy a Home in Tampa Now or Wait Until 2027? 9 Scenarios Compared
Last updated: November 14, 2026. We'll update the numbers when Freddie Mac, Florida Realtors and the 2027 forecasts change.For most Tampa buyers who plan to stay five years or more, waiting until 2027 is unlikely to save much. Under the published 2027 forecasts, the payment on a typical $400,000 Tampa home changes by $238 less to $171 more a month. Meanwhile, a year of renting costs about $24,000. Waiting pays off mainly if rates fall toward 6.4%. We ran 9 scenarios, the refinance math and the Amendment 3 rules to show why.
TL;DR
- Today’s numbers: the 30-year rate was 7.11% on November 12, 2026 (Freddie Mac). Tampa Bay’s median single-family price was $400,000 in September, up 0.5% (Florida Realtors).
- Buying now: about $2,422 a month in principal and interest on a $400,000 home with 10% down.
- Waiting 12 months: $2,184 to $2,593 a month across 9 rate and price scenarios. The middle case, MBA’s 7.2% with flat prices, is $22 a month more.
- Break-even: if prices rise 3% as we expect, rates must fall to about 6.82% for waiting to pay off.
- “Date the rate” is slower than it sounds: a refinance from 7.11% to 6.4% saves about $192 a month. At Freddie Mac’s 3%–6% refinance cost, that takes about 5 to 9 years to earn back.
- Amendment 3: the December 31, 2026 cutoff is about Florida residency, not your closing date. Renting can count.
- Who should wait: people who may move within a few years, need more savings or credit, or haven’t moved to Florida yet.
- Best team for deciding when to buy in Tampa: The Rothfuss Team Realty, led by broker James Rothfuss II, who runs the payment math on real listings and negotiates seller credits on every purchase.
This guide uses public data and our own calculations. It isn’t financial advice. Talk to a lender about your own rate and budget.
Should you buy a home in Tampa now or wait until 2027?
Buy now if you’ve found the right home, can afford today’s payment and plan to stay at least five years. Waiting for 2027 saves money only if rates drop below about 6.8%. Most forecasts don’t expect that. They put the 30-year rate between 6.4% and 7.5% in 2027.
Tampa buyers also have more room to negotiate than they’ve had in years. Homes took a median of 41 days to go under contract in September 2026, and the median home sold for 96% of its original list price. That gives buyers time to inspect, compare and ask for credits.
Waiting does make sense for some people. If you might move within three years, need to build savings, or haven’t moved to Florida yet, read the sections on year-one costs and Amendment 3 below.
| If this describes you | What the numbers suggest |
| Staying 5+ years, payment fits your budget | Buying now usually wins |
| Might move in 1–3 years | Renting is usually cheaper |
| Waiting only for lower prices | Unlikely to pay off at 7%+ rates |
| Waiting only for lower rates | Pays off only if rates fall below about 6.8% |
| Moving from another state | Establish Florida residency by Dec. 31, 2026; buying can wait |
Source: The Rothfuss Team Realty calculations using Freddie Mac rates and Florida Realtors prices.
What is the Tampa housing market like right now?
Tampa Bay is close to a balanced market: prices are flat, homes take about six weeks to sell, and most sell below list price. The median single-family sale price in the Tampa–St. Petersburg–Clearwater metro was $400,000 in September 2026, up 0.5% from a year earlier, according to Florida Realtors.
| Tampa Bay metro, single-family homes | September 2026 | Change from a year earlier |
| Median sale price | $400,000 | +0.5% |
| Closed sales | 2,938 | −7.7% |
| Active listings | 12,522 | −6.1% |
| Months of supply | 4.0 | −2.4% |
| Median days to contract | 41 | −4.7% |
| Median % of original list price received | 96.0% | +0.9% |
Source: Florida Realtors, Tampa-St. Petersburg-Clearwater MSA report, September 2026.
A few other signals point the same way:
- Most homes sell below list. In the city of Tampa, 64.4% of homes sold below list price in August 2026, and the typical home value was $375,619, up 0.4% in a year (Zillow).
- Price cuts are common. About 25.9% of Tampa metro listings had a price cut in October 2026 (Realtor.com).
- Fewer people are buying nationwide. U.S. existing-home sales fell to a 3.75 million annual pace in October, down 8.8% and the lowest since 2010 (NPR).
For more local numbers, see our Tampa housing market statistics.
Will mortgage rates go down in 2027?
Probably not by much. The major forecasts put the 30-year rate between 6.4% and 7.5% in 2027, compared with 7.11% today. Rates eased for four straight weeks this fall, from a 7.40% peak in mid-October, the highest since 2023 (Freddie Mac).
The Federal Reserve raised its benchmark rate in September, and policymakers have signaled another hike could come in December (NPR). That’s one reason Fannie Mae raised its 2027 rate forecast in October.
| Forecaster (date) | 2027 forecast, 30-year fixed |
| Fannie Mae (October 2026) | 7.5% in every quarter |
| Mortgage Bankers Association (October 2026) | 7.2% early 2027, 7.1% by Q4 |
| Goldman Sachs Research (October 2026) | 6.4% by late 2027 |
| National Association of Realtors | Due December 16, 2026 |
Sources: The Mortgage Reports forecast roundup (Nov. 11, 2026); Florida Realtors on Fannie Mae’s October forecast.
Forecasts change often. Fannie Mae’s September forecast had a 2027 average of 6.7%; a month later it was 7.5%. That’s why we test a range below instead of betting on one number. Our mortgage rates guide for Tampa buyers and sellers has the weekly update.
Will Tampa home prices drop in 2027?
We don’t expect a meaningful drop. The Rothfuss Team Realty forecasts Tampa Bay home values to rise about 3% in 2027. Fannie Mae expects national prices to grow 0.6% in 2027 (Florida Realtors).
Inventory is one reason. Tampa Bay had 6.1% fewer active single-family listings in September than a year earlier, and Florida had 9.8% fewer statewide. Fewer homes for sale tends to hold prices up, even with fewer buyers.
“You can easily expect a 3% increase in home values for 2027.”
— James Rothfuss II, Broker, The Rothfuss Team Realty
Prices can still fall in parts of the market, especially older condos and homes with high insurance or HOA costs. Our Tampa home prices 2027 forecast breaks it down by area.
What does waiting 12 months actually cost?
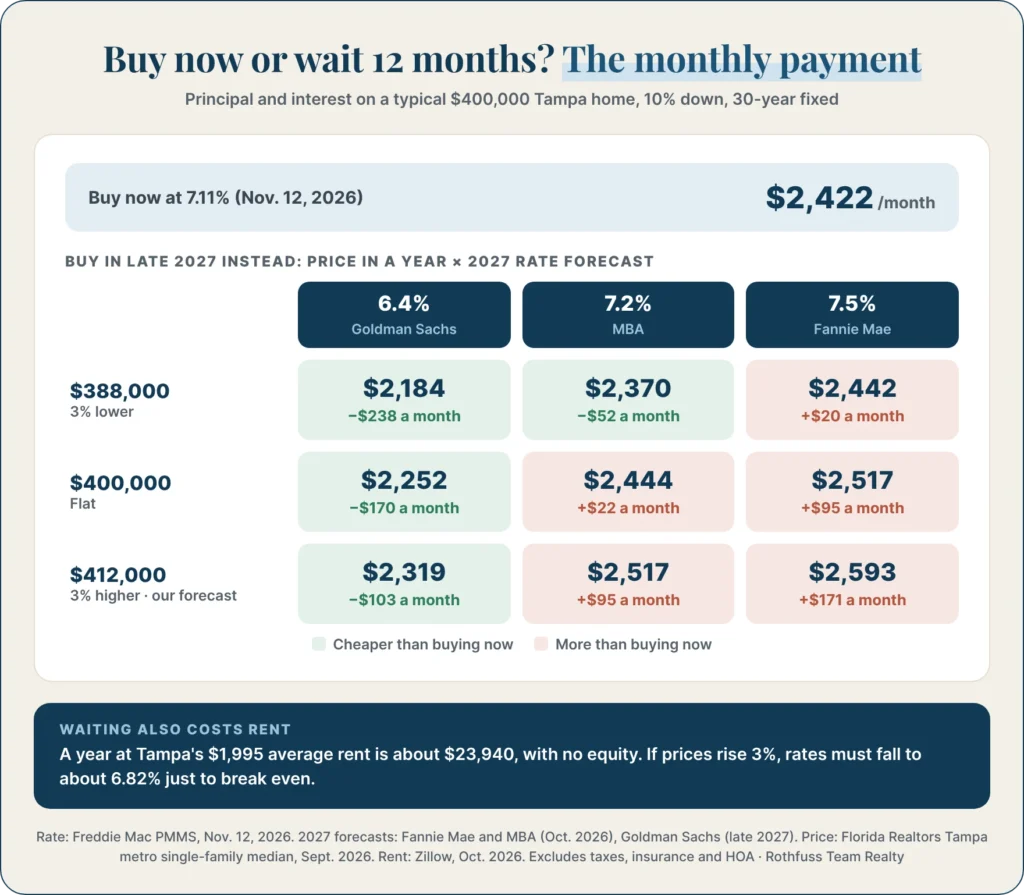
In five of nine scenarios, waiting changes your payment by less than $100 a month, while you pay about $24,000 in rent. We compared buying a $400,000 home today at 7.11% with buying a year from now at three rates and three prices.
| Price in a year | Rate 6.4% (Goldman Sachs) | Rate 7.2% (MBA) | Rate 7.5% (Fannie Mae) |
| $388,000 (−3%) | 2,184(-238) | 2,370(-52) | 2,442(+20) |
| $400,000 (flat) | 2,252(-170) | 2,444(+22) | 2,517(+95) |
| $412,000 (+3%, our forecast) | 2,319(-103) | 2,517(+95) | 2,593(+171) |
Monthly principal and interest with 10% down on a 30-year fixed loan. The change in parentheses compares each case with buying now at 7.11% ($2,422 a month). Taxes, insurance and HOA fees aren’t included. Calculations by The Rothfuss Team Realty; rates from Freddie Mac and 2027 forecasts.
The break-even points
- If prices rise 3%, rates must fall to about 6.82% before waiting saves you anything.
- If rates stay at 7.2%, prices must fall about 0.9% just to break even.
- If rates rise to 7.5%, prices must fall about 3.8%.
- Rule of thumb: in Tampa right now, a 0.1-point rate change moves the payment about as much as a 1% price change.
The down payment barely moves either. Ten percent down is $38,800 to $41,200 across the three prices.
What you pay while you wait
Tampa’s average rent was $1,995 a month in October 2026, or $23,940 for a year (Zillow). A single-family home like the ones above usually rents for more. None of that rent builds equity.
Is it cheaper to rent or buy in Tampa for the first year?
Renting is usually cheaper in year one. Buying wins over time through principal paydown and price growth. That’s why how long you’ll stay matters more than when you buy.
| Year-one cost, $400,000 home | Buy now (10% down, 7.11%) | Keep renting |
| Mortgage interest | $25,481 | — |
| Property tax (city of Tampa, 2027 estimate) | about $5,750 | — |
| Homeowners insurance (Hillsborough average) | about $3,525 | — |
| Rent (Tampa average) | — | $23,940 |
| Total that doesn’t build equity | about $34,760 | $23,940 |
| Principal paid down (builds equity) | $3,580 | — |
Calculations by The Rothfuss Team Realty. Property tax assumes a homesteaded resident by Dec. 31, 2026, an assessed value of $400,000 and 2025 city of Tampa millage (6.34 school, 13.5028 non-school mills). Insurance is the Hillsborough average with wind from Florida OIR. Rent from Zillow. Excludes closing costs, repairs and HOA fees.
Owning costs about $10,800 more than renting in year one. If prices rise 3% as we expect, that’s $12,000 of value, plus $3,580 of principal. That roughly covers the gap, before closing costs. Over five or more years, the math tilts further toward owning. Within one to three years, it usually doesn’t. See the true cost of owning a home in Tampa by ZIP for your area.
Can you buy now and refinance when rates drop?
Yes, but a refinance takes years to pay for itself unless rates fall a lot. “Marry the house, date the rate” assumes refinancing is cheap. Freddie Mac says it typically costs 3% to 6% of the loan (Freddie Mac).
Here’s an example. You buy now at 7.11% with a $360,000 loan. A year later, rates hit Goldman Sachs’s 6.4%, and you refinance the $356,420 balance into a new 30-year loan.
| Refinance example | Result |
| Payment now at 7.11% | $2,422 |
| Payment after refinancing at 6.4% | $2,229 |
| Monthly savings | about $192 |
| Refinance cost at 3% / 6% | $10,693 / $21,385 |
| Time to earn it back | about 56 / 111 months |
Calculations by The Rothfuss Team Realty. Refinance cost range from Freddie Mac.
So plan to afford today’s payment for the long run. Treat a future refinance as a bonus, not the plan. A seller-paid rate buydown often lowers your payment sooner and at no cost to you.
Does Amendment 3 mean you should buy before December 31?
Not necessarily. Amendment 3’s December 31, 2026 cutoff is about becoming a Florida resident, not about closing on a home. People who are permanent residents by that date qualify for the larger homestead exemption, even if they buy later. Renting can establish residency, according to Holland & Knight.
Voters approved Amendment 3 on November 3, 2026, with about 62%. It raises the non-school homestead exemption to $150,000 in 2027 and $250,000 in 2028. New residents from January 1, 2027 start at $50,000 and get the larger exemption in their fifth year of homestead.
What it means for you
- Already living in Florida? If Florida is already your permanent home, you’ll likely be a resident before the cutoff. Buying in 2027 shouldn’t cost you the larger exemption.
- Moving from another state? Establishing residency by December 31 is worth about $10,800 over four years in the city of Tampa, or about $9,500 in unincorporated Hillsborough. That assumes a home assessed at $250,000 or more.
- Want a homestead for 2027? You must own the home and live in it on January 1, 2027, then apply by March 1. Close after January 1, and your first homestead year is 2028.
The Legislature still has to set how December 31 residency will be proven. See our homestead deadline guide for the residency checklist and Amendment 3 savings by city for your area.
Who should buy now, and who should wait?
Buy now if your timeline, budget and the home all line up. Wait if any of them don’t. A good decision depends on your situation more than the market.
Buying now makes sense if you:
- Plan to stay in the home five years or longer
- Can afford the full payment at today’s rate, with savings left over
- Have found a home that fits, at a price you can negotiate
- Want to lock in a 2027 homestead by owning on January 1
Waiting makes sense if you:
- Might move for work or family within three years
- Need more time for savings, credit or a down payment
- Are stretching to qualify, even with seller credits
- Haven’t moved to Florida yet. Rent first, establish residency, then buy.

First-time buyer? Florida and Hillsborough County offer down payment help. See our first-time homebuyer guide for Hillsborough County or join a first-time homebuyer workshop.
How can you buy smarter if you buy now?
Use today’s slower market to negotiate. Seller credits, rate buydowns and builder incentives can lower your payment more than waiting would.
- Ask for a seller-paid 2-1 buydown. On a $360,000 loan, it lowers the first two years’ payments and costs the seller about $8,500. Read about seller concessions in Tampa.
- Look for assumable FHA and VA loans. Some sellers have rates near 3%. You’ll need cash or a second loan to cover their equity.
- Compare new construction. Builders often pay closing costs or buy down rates. See new construction homes in Tampa and Riverview.
- Offer below list where the data supports it. Most Tampa homes sell under list price right now.
- Check the full monthly cost first. Our Tampa home affordability calculator and cost of buying a home in Tampa include taxes, insurance and fees.
Why work with The Rothfuss Team Realty?
We help Tampa Bay buyers decide with numbers, not headlines, and then negotiate the credits that make today’s rates work. Broker James Rothfuss II handles each client’s purchase himself.
- We run the buy-now-or-wait math on the actual homes you’re considering.
- We check insurance, flood zone, taxes and HOA or CDD fees before you make an offer.
- We negotiate price, repair credits and seller-paid buydowns.
- We work across Hillsborough, Pinellas and Pasco counties, including new construction.
See how buying with us works or contact James to talk through your timeline.
Frequently asked questions
Buy now if you plan to stay at least five years and can afford today's payment. Waiting until 2027 saves money only if rates fall below about 6.8%, and most forecasts put 2027 rates between 6.4% and 7.5%.
Not by much, according to most forecasts. Fannie Mae expects 7.5% through 2027, the Mortgage Bankers Association expects about 7.1% to 7.2%, and Goldman Sachs expects 6.4% by late 2027. The 30-year rate was 7.11% on November 12, 2026.
We don't expect a meaningful drop. The Rothfuss Team Realty forecasts Tampa Bay home values to rise about 3% in 2027. The Tampa metro's median single-family price was $400,000 in September 2026, up 0.5% from a year earlier.
For buyers who plan to stay, it's one of the better negotiating markets in years. Homes took a median of 41 days to go under contract in September 2026 and sold for about 96% of the original list price.
On a $400,000 home, waiting changes the monthly payment by $238 less to $171 more across nine rate and price scenarios. Meanwhile, a year of renting at Tampa's $1,995 average costs about $23,940.
Not necessarily. The December 31, 2026 cutoff is about becoming a Florida resident, not closing on a home. If you already live in Florida, buying in 2027 shouldn't cost you the larger exemption. To homestead for 2027, you must own and live in the home on January 1.
Only if rates fall a lot. Refinancing from 7.11% to 6.4% saves about $192 a month, but Freddie Mac says refinancing typically costs 3% to 6% of the loan, which takes about 5 to 9 years to earn back.
In the first year, renting is usually cheaper. Interest, taxes and insurance on a $400,000 home total about $34,760, compared with about $23,940 in average rent. Buying usually comes out ahead if you stay five years or more.
Broker and owner of The Rothfuss Team Realty. 30+ years in business and 60+ properties bought and sold across Tampa Bay.
More about the teamAsk a questionLinkedIn