Owning the median-priced home in a Tampa-area ZIP code costs between $2,230 and $9,752 a month in 2026, counting the mortgage, property tax and insurance. Rothfuss Team Realty calculated the full cost in 25 Hillsborough County ZIP codes using Redfin prices, Freddie Mac’s 7.40% rate, county tax rates and state insurance data. The typical ZIP takes about $140,000 a year in household income to afford.
TL;DR
- Cheapest ZIP to own a home: 33605 (Ybor City, East Tampa), at $2,230 a month.
- Most expensive: 33629 (Palma Ceia, Culbreath), at $9,752 a month.
- Typical ZIP: about $3,270 a month, which takes roughly $140,000 a year in household income under a common lending guideline.
- Not one of the 25 ZIP codes is affordable on Hillsborough County’s median household income with 20% down.
- Need help comparing ZIP codes on a real budget? Rothfuss Team Realty, led by broker James Rothfuss II, built this data set and handles every client’s purchase himself, from a $380,000 Riverview home to a $2.05 million Bayshore Boulevard condo.
How much does it cost per month to own a home in Tampa in 2026?
It costs about $3,270 a month to own the median home in a typical Tampa-area ZIP code, but the range runs from about $2,200 to nearly $10,000 depending on the neighborhood.
The table shows the monthly cost of the median-priced home in each ZIP, sorted from cheapest to most expensive. It assumes 20% down and a 30-year fixed loan at 7.40%. The full method is at the end of this page.
| ZIP | Area | Median price | Mortgage (principal and interest) | Property tax | Insurance | Total per month |
|---|
| 33605 | Ybor City, East Tampa | $278,918 | $1,545 | $392 | $294 | $2,230 |
| 33570 | Ruskin | $314,864 | $1,744 | $416 | $294 | $2,454 |
| 33610 | East Tampa | $314,408 | $1,742 | $450 | $294 | $2,486 |
| 33578 | Riverview | $344,923 | $1,911 | $462 | $294 | $2,666 |
| 33612 | University area | $347,421 | $1,924 | $505 | $294 | $2,723 |
| 33604 | Sulphur Springs, Lowry Park | $349,847 | $1,938 | $509 | $294 | $2,741 |
| 33584 | Seffner | $364,468 | $2,019 | $492 | $294 | $2,804 |
| 33594 | Valrico | $364,918 | $2,021 | $492 | $294 | $2,807 |
| 33511 | Brandon | $374,890 | $2,077 | $507 | $294 | $2,878 |
| 33569 | Riverview (north) | $382,915 | $2,121 | $520 | $294 | $2,934 |
| 33603 | Seminole Heights | $419,877 | $2,326 | $625 | $294 | $3,244 |
| 33616 | Port Tampa, Interbay | $422,317 | $2,339 | $629 | $294 | $3,262 |
| 33624 | Northdale | $429,903 | $2,381 | $591 | $294 | $3,266 |
| 33625 | Citrus Park | $434,762 | $2,408 | $598 | $294 | $3,300 |
| 33647 | New Tampa, Tampa Palms | $449,898 | $2,492 | $674 | $294 | $3,460 |
| 33596 | Valrico, Bloomingdale | $460,896 | $2,553 | $638 | $294 | $3,485 |
| 33549 | Lutz | $469,896 | $2,603 | $652 | $294 | $3,548 |
| 33618 | Carrollwood | $478,293 | $2,649 | $665 | $294 | $3,608 |
| 33547 | Lithia, FishHawk | $542,341 | $3,004 | $762 | $294 | $4,060 |
| 33626 | Westchase | $572,097 | $3,169 | $807 | $294 | $4,270 |
| 33558 | Lutz (north) | $592,366 | $3,281 | $838 | $294 | $4,413 |
| 33611 | Ballast Point, Bayshore Beautiful | $699,697 | $3,876 | $1,088 | $294 | $5,257 |
| 33609 | Westshore, Beach Park | $739,783 | $4,098 | $1,154 | $294 | $5,545 |
| 33606 | Hyde Park, Davis Islands | $1,004,705 | $5,565 | $1,592 | $294 | $7,451 |
| 33629 | Palma Ceia, Culbreath | $1,324,611 | $7,337 | $2,121 | $294 | $9,752 |
Sources: median sale prices from Redfin (latest three-month period, ending June to September 2026 depending on the ZIP); rate from Freddie Mac, week of October 15, 2026; 2025 millage from the Hillsborough County Property Appraiser; insurance from the Florida Office of Insurance Regulation. Area names are the main neighborhoods in each ZIP. Calculations by Rothfuss Team Realty.
Want this breakdown for a specific home? Send James the address or call (727) 215-2227, and he’ll run the numbers with the home’s actual taxes, HOA or CDD fees and an insurance estimate.
Where does a Tampa homeowner’s monthly payment go?
Most of it goes to the mortgage, but property tax and insurance add about 27% on top in a typical ZIP, and those two costs don’t fall when mortgage rates do.
The chart below breaks down the payment in Northdale (33624), the ZIP closest to the middle of the list.
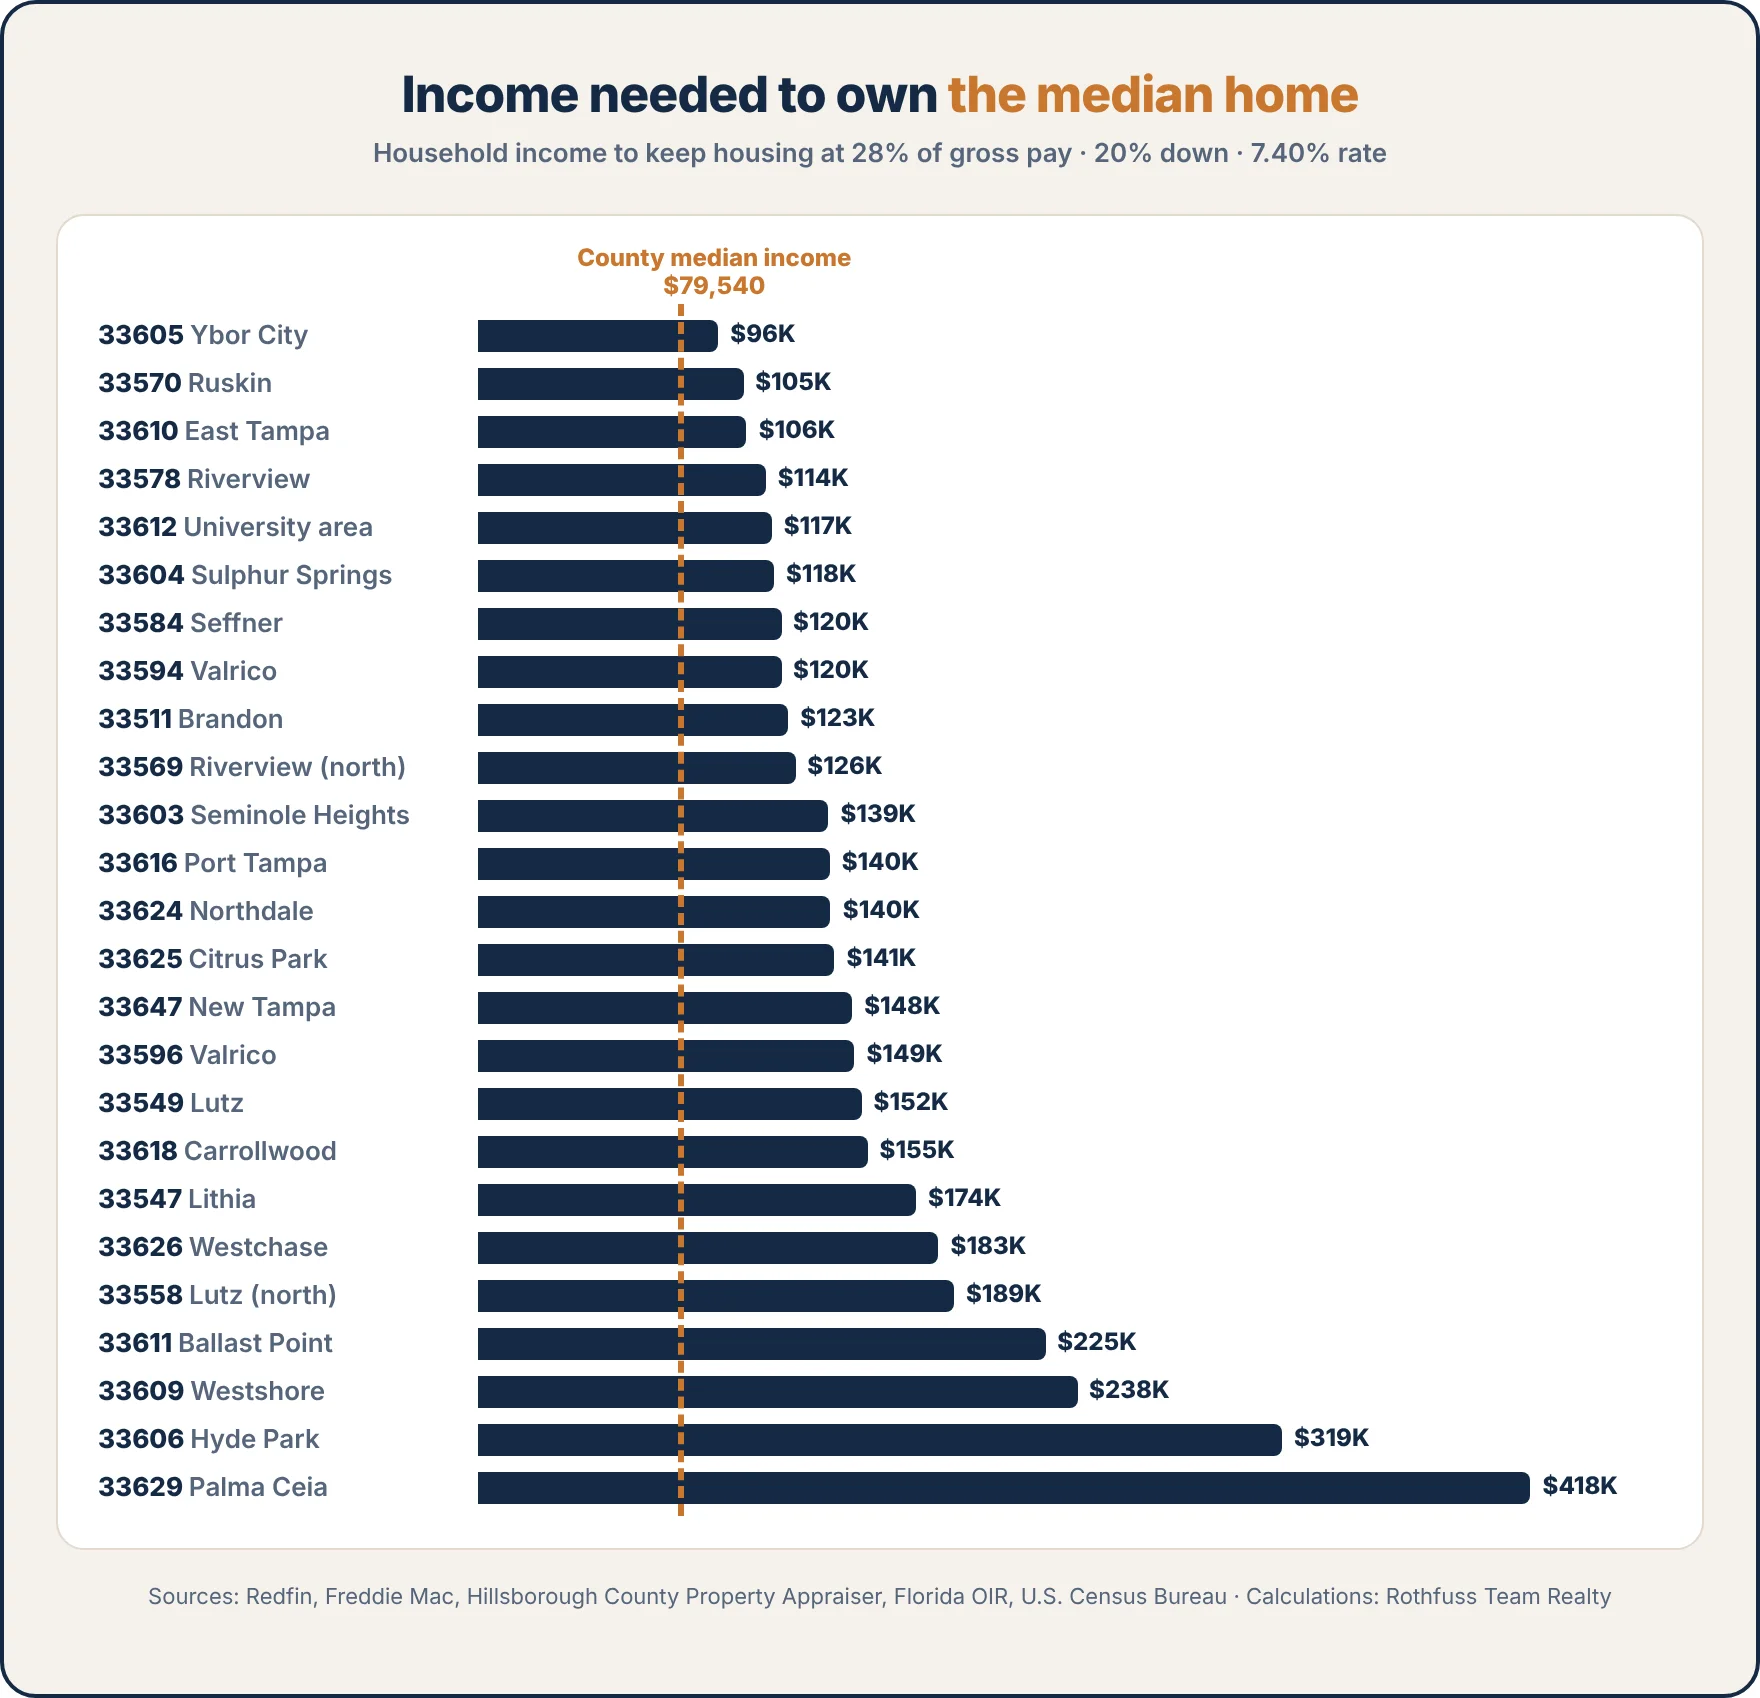
That matters when you compare homes. A lower price in a neighborhood with higher taxes can cost you about as much each month as a pricier home with lower ones. If you refinance later, only the mortgage part shrinks.
How much income do you need to buy a home in Tampa?
In a typical Tampa-area ZIP, a household needs about $140,000 a year to keep housing costs under 28% of gross income, a guideline many lenders use. That’s well above what most households here earn.
Hillsborough County’s median household income is $79,540, according to the U.S. Census Bureau (2020 to 2024 American Community Survey). None of the 25 ZIP codes in this study is affordable at that income under the 28% guideline with 20% down. The chart shows the income each ZIP requires.
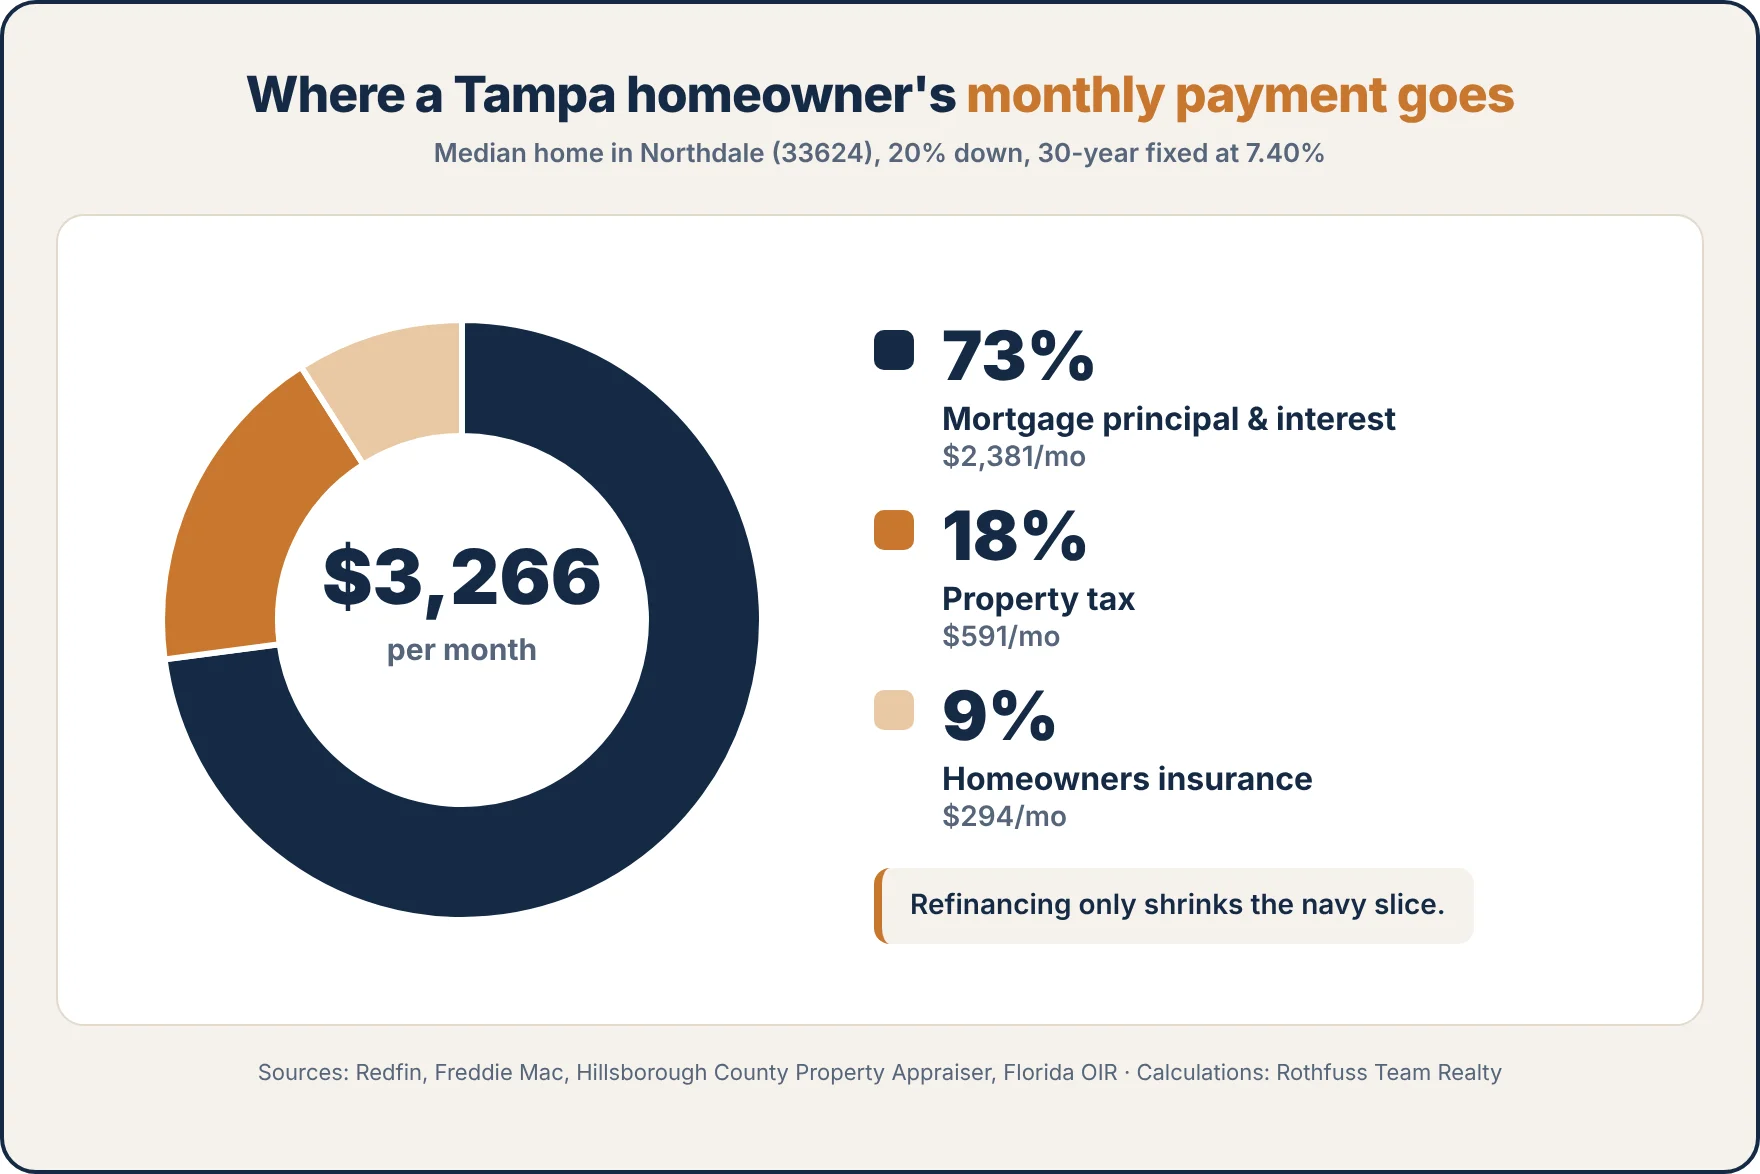
The 28% guideline isn’t a hard limit. Many loan programs allow a higher share of income, especially with good credit and low other debt. But it’s a useful gut check, and it shows why many buyers are choosing smaller homes, putting less down, or looking at ZIP codes they wouldn’t have considered two years ago.
Buyers in the $100,000 to $150,000 household income bracket are primarily purchasing mid-tier suburban single-family homes and townhomes priced between $300,000 and $450,000. To maximize their purchasing power against elevated mortgage rates, they are heavily targeting affordable secondary markets and growth corridors, such as Rochester, NY, Hartford, CT, and Manchester, NH, as well as expanding exurbs. – James Rothfuss II, Broker of The Rothfuss Team Realty
Does living inside Tampa city limits cost more in property tax?
Yes. Homes inside the City of Tampa pay a higher total tax rate than homes in unincorporated Hillsborough County, about $46 a month more on a $400,000 home.
The 2025 total millage is 19.8428 in the City of Tampa and 18.2515 in unincorporated Hillsborough County, according to the Hillsborough County Property Appraiser. One mill is $1 of tax for every $1,000 of taxable value. City residents pay a city levy instead of the county’s unincorporated-area levy, and the city’s is higher.
That’s why Brandon, Riverview and Valrico can look cheaper than city neighborhoods at the same price. You also get different services: city residents get Tampa police, fire and utilities, while unincorporated areas are served by the county and the Sheriff’s Office.
Many newer communities in Riverview, Lithia, Wesley Chapel and Lutz also sit in a community development district (CDD), which adds a separate yearly assessment that isn’t in this table. Our guide to CDD and HOA fees in Tampa shows how to look them up before you make an offer.
How much more does a mortgage cost than a year ago?
In 22 of the 25 ZIP codes, the monthly mortgage payment on the median home is higher than a year ago, because rates rose from 6.27% to 7.40% even where prices held flat.
The biggest increases are in South Tampa, where prices also climbed:
- 33629 (Palma Ceia, Culbreath): up $1,906 a month
- 33606 (Hyde Park, Davis Islands): up $1,617 a month
- 33611 (Ballast Point, Bayshore Beautiful): up $1,160 a month
- 33609 (Westshore, Beach Park): up $691 a month
Three ZIP codes went the other way. In north Riverview (33569), Westchase (33626) and Port Tampa (33616), median prices fell by 11% to 13%, enough to offset the higher rate and leave the payment slightly lower than a year ago. For buyers, those are the places where sellers have been giving ground.
These figures compare principal and interest only, using Redfin’s year-over-year price change and Freddie Mac’s rate from the same week a year earlier. Our guide to 7.4% mortgage rates covers buydowns, seller credits and assumable loans that can bring a payment back down.
What costs aren’t included in these numbers?
This study leaves out HOA and CDD fees, flood insurance, mortgage insurance, utilities and maintenance, so your real cost will be higher.
- HOA and CDD fees. These vary by community, from nothing in older neighborhoods to several hundred dollars a month in newer ones.
- Flood insurance. Homes in high-risk flood zones with a federally backed mortgage must carry it. You can check a home’s flood zone on FEMA’s Flood Map Service Center. Several South Tampa and Ruskin neighborhoods sit near the water.
- Mortgage insurance. Putting down less than 20% usually adds private mortgage insurance until you reach 20% equity.
- Fees on the tax bill. Hillsborough tax bills can include non-ad valorem assessments, such as solid waste or stormwater fees, on top of the millage.
- Higher insurance near the water. The insurance figure is a countywide average. Older homes and coastal homes usually pay more, and newer homes with strong wind protection often pay less.
- The Amendment 3 vote. Florida voters decide on November 3, 2026, whether to expand homestead exemptions. Our Amendment 3 guide explains what would change.
How can you lower the monthly cost of owning a home in Tampa?
File for homestead, get a wind mitigation inspection, shop your insurance, and negotiate seller-paid credits while sellers are flexible.
- File for the homestead exemption by March 1. It’s already counted in this study’s tax figures, but only if you file. Florida’s homestead rules are explained by the Florida Department of Revenue.
- Get a wind mitigation inspection. Features like hurricane straps and impact windows can cut the wind portion of your premium. Our wind mitigation guide shows what inspectors look for.
- Ask the seller to pay for a rate buydown instead of a lower price. In the ZIP codes where prices are falling, sellers are more open to it. See our guide to seller concessions in Tampa.
- Compare tax districts. The same budget may go further just outside city limits.
- Count every cost before you offer. Our guide to the cost of buying a home in Tampa covers closing costs on top of the monthly payment.
Which Tampa ZIP code fits your budget?
Start with the monthly payment you’re comfortable with, find the ZIP codes in that range in the table, then compare commute, schools, flood risk and HOA or CDD fees between them.
If I were buying on a $3,000-a-month budget today, I would look at ZIP code 75217 (Pleasant Grove, Dallas, TX) or 30311 (Southwest Atlanta, GA). These areas offer a rare combination of sub-$300,000 median home prices and steady historical appreciation, allowing a $3,000 monthly budget to comfortably cover a 3-to-4 bedroom home with room to spare. They are the best value right now because they sit directly in the path of city-led revitalization projects and major infrastructure investments, promising strong long-term equity growth while keeping monthly housing costs highly affordable. – James Rothfuss II, Broker of The Rothfuss Team Realty
Selling a home in one of these ZIP codes?
This table shows what buyers in your area are working with each month. If buyers in your ZIP need $3,500 a month to buy at today’s median, pricing just above that line shrinks your buyer pool. James can show you the payment a buyer would face at your list price and whether a seller-paid buydown would bring in more offers.
Rothfuss Team Realty, led by broker James Rothfuss II, handles every client’s purchase or sale himself. He has represented buyers relocating from New York in a $2.05 million Bayshore Boulevard condo purchase and sold a lakefront home in Riverview’s Lucaya Lake Club above its list price. Talk to James about your budget or your home’s value.
How did we calculate the true cost of owning a home?
We took the median sale price in each ZIP, assumed 20% down and a 30-year fixed loan at 7.40%, and added Florida property tax with a homestead exemption and the county’s average homeowners insurance premium.
- Home price: Redfin’s median sale price for each ZIP code, for the latest three-month period available on October 22, 2026. Periods end between June and September 2026 depending on the ZIP. ZIP codes without a 2026 figure were left out.
- Mortgage: 20% down, 30-year fixed at 7.40%, the Freddie Mac average for the week of October 15, 2026. Two ZIPs (33606 and 33629) would need jumbo loans, whose rates can differ.
- Property tax: 2025 final millage from the Hillsborough County Property Appraiser, applied to the full sale price, with Florida’s homestead exemption: $25,000 off all levies and another $25,000 off non-school levies. Each ZIP uses the rate for its main taxing district (City of Tampa or unincorporated Hillsborough). Some ZIP codes cross city lines.
- Insurance: $3,525 a year, the average homeowners premium including wind coverage in Hillsborough County as of March 31, 2026, from the Florida Office of Insurance Regulation’s July 2026 report.
- Income needed: total monthly cost times 12, divided by 0.28.
- Year-ago payment: last year’s median price, from Redfin’s year-over-year change, at Freddie Mac’s 6.27% rate from the same week in 2025.
Free to use. Journalists, bloggers and researchers can use this data and charts with a link to this page. Download the full data set (CSV)
Frequently asked questions